
Family office benchmarks will tell you that running an office costs somewhere between 40 and 50 basis points of assets a year. Priced in full, it is closer to four times that.
The benchmarks are not wrong. They measure the cost of running the office: people, advisers, systems, premises. What the family pays to have its money invested is left out, and in most offices nobody has ever put the two figures side by side.
This is what we find, consistently, in the single family offices we are brought in to run or reset: the running cost has been budgeted, scrutinised and benchmarked against other family offices for years. What the office pays outward to invest, across managers, funds and custodians, has never been assembled in one place. Each provider is judged against itself.
Who writes about fees, and from where
Most of what is published on family office fees comes from the banks. J.P. Morgan's 2026 survey of 333 single family offices across 30 countries puts external costs at 25% to 28% of the total budget. UBS's 2025 report, on 317 offices, gives the office's own running cost at around 41 basis points of assets, closer to 35 above $1bn.
Read the perimeter, though. "External costs" in these reports means the fees that pass through the office's budget: the lawyers, the auditors, the administrator, the consultants. The management fee on a discretionary mandate, the fee layers inside a private equity fund, the custody charge, the carry, sit outside the budget and outside the survey. UBS itself notes that "pure cost", the figure everyone quotes, is only about 57% of what a family office spends once asset management fees and banking charges are counted. The remaining 43% is largely what managers, banks and custodians are paid, the institutions that publish the surveys among them.
We come at this from the other side of the table. Our partners have built family offices, sat in the CEO's or CIO's chair, and signed the invoices on behalf of families. The model behind our family office cost calculator is drawn from those offices: what they pay their people, what they pay their providers, what each pocket of the portfolio costs to hold, country by country.
Five ways an external firm gets paid
Almost every fee a family pays outward takes one of five forms, or blends several of them.
The first is a percentage of assets. It is the standard in portfolio management and the least legible of the five, because the invoice grows with the portfolio while the work stays roughly where it was. Sixty basis points on $400m is $2.4m a year. The same rate on $700m is $4.2m.
The second is a fixed fee, agreed for a defined scope over a defined period. It is normal in administration, accounting and company secretarial work, and it has been spreading into advisory work. Its virtue is that the family knows the number before the year begins.
The third is time. Lawyers and tax advisers bill this way, and for episodic work it is the honest model. It becomes expensive when it is used for something continuous, because nobody inside the office can forecast it and nobody outside is asked to.
The fourth is a fee on an event: a percentage of a transaction, a success fee on a sale, a fee on capital committed. It puts the firm behind getting the deal done. That helps when the family wants the deal done and hurts when the right answer is to walk away.
The fifth is money the firm receives from someone other than the family. Retrocessions on funds, trailer commissions, platform rebates, foreign exchange spreads, fee layers inside a vehicle the family is already invested in. The family pays all of it, usually without knowing.
Most real arrangements blend several of these. A bank might charge a percentage of assets, bill separately for anything outside the core mandate, and receive a rebate on the funds it selects. Each element is reasonable on its own. The combination can add up to more than the family expected, because no single document shows all three at once.
The half of the bill that is not in the budget
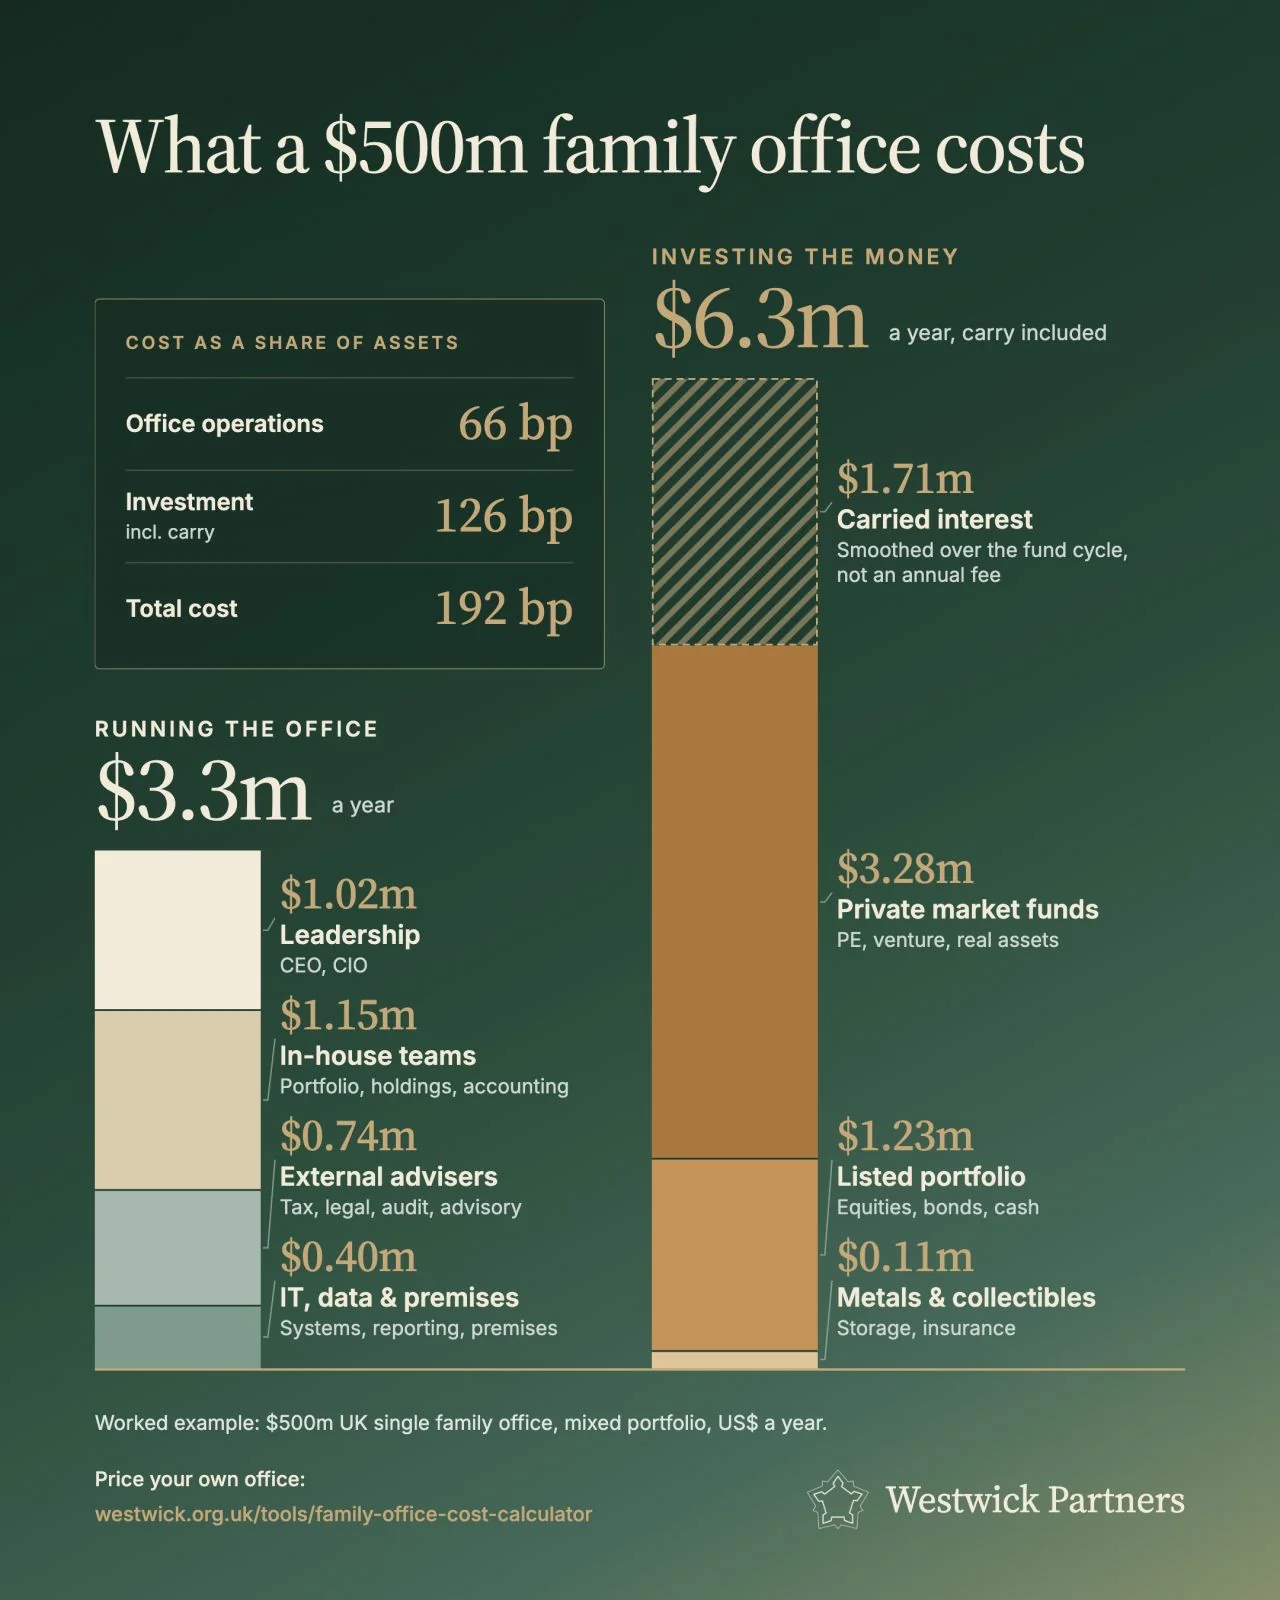
Take a hypothetical single family office: $500m of assets, based in the United Kingdom, serving four family members across two jurisdictions. Half the portfolio in listed equities and bonds, close to a third in private equity, venture and real asset funds, a tenth in three direct holdings (one of them controlled), a few per cent in metals and collectibles, the rest in cash. Investment oversight and accounting are kept in-house; execution is split between the office and its banks; tax, legal and IT are bought in.
Our calculator prices that office at about $3.3m a year to run, in a range of roughly $2.6m to $4.1m, with about two-thirds of it going to leadership and the in-house teams. That is the number the surveys measure. Here it works out at 66 basis points, well above their average of about 40 for an office this size: direct holdings, one of them controlled, cost more to run than the average office the surveys describe.
Then it prices what the same family pays to invest. Management fees to the managers of each pocket, the fee layers embedded in the funds, custody, trading, the cost of selecting and monitoring the managers: about $4.6m a year. Carried interest, spread over the life of the funds rather than counted in the year it crystallises, adds about $1.7m more. Call the investment layer $6.3m, or 126 basis points. Even with the carry taken out, it costs more than running the office.
So the family pays roughly $3.3m to run the office and $6.3m to have its money managed, 192 basis points in all, before a single return is booked. The investment layer is close to twice the running cost. In a median year on that allocation, with a gross return in the region of 8.5%, the two layers together take more than a fifth of the gain.
Two qualifications. On a purely listed portfolio of the same size (60% equities, 30% bonds, the rest in cash), the calculator puts the office at about $1.6m a year and the investment layer at about $2m: much closer to parity. Complexity, not size, is what tips the balance. And the running cost is the one the office controls directly. It is also the smaller one, and the one that gets the scrutiny.
This is one office. Two families with the same assets can differ by half again in cost, depending on how the portfolio is allocated, what the office keeps in-house and what it buys, and how lean the organisation is. The calculator takes all three into account.
Write the percentage in money
A rate is not a price. Families sign rates and pay amounts, and almost nobody converts one into the other before signing.
Take $200m of that $500m under a discretionary mandate at 70 basis points. That is $1.4m a year. Move the rate to 40 basis points and the family keeps $600,000 a year. Assume the portfolio compounds at 8% a year gross, an assumption worth stating rather than burying, and over ten years the difference in terminal value is about $11m.
That is one line, on 40% of one portfolio. Running the same arithmetic across custody, administration and the fund layer usually produces a larger number than the mandate did. It is also the arithmetic the calculator's full analysis does for you, pocket by pocket, on your own allocation.
How the bill compares with other advisers
Families often ask how the cost of running an office compares with what a wealth adviser charges. The two numbers measure different things.
The office's 41 basis points cover salaries, premises and systems. They stop there. The fees the office then pays to managers, banks, lawyers and administrators sit on top, and for most portfolios they are the larger half. An external adviser quotes a single rate that covers its operation and its judgement together. Set that rate against the office's 41 basis points and the office looks cheap, which is the wrong conclusion drawn from the right data. Set it against the office's running cost plus everything the office pays outward and the comparison starts to mean something.
This is the arithmetic that should sit behind any decision to outsource part of the office, and it is usually done in the other order. The provider gets chosen, then the family works out what it is paying.
Fee model matters more than fee level in that comparison. A rate that is competitive on paper but paid as a percentage of assets will overtake a higher fixed fee within a few years of decent markets, without anyone deciding that it should. This is the first question to put to any firm the family is considering as an adviser, well before track record and fit.
The part of the bill that never arrives
Fees have become the leading complaint families make about private markets. Among 175 single family offices surveyed by BlackRock in 2025, 72% named high fees as their main difficulty in private equity, against 40% in the previous edition. Very little of that money is invoiced. It sits inside the fund: management fees charged on committed rather than invested capital, transaction and monitoring fees charged down at the portfolio company, carry crystallising on valuations the family cannot test.
The same pattern runs through the rest of the bill. Custody charged in basis points on a balance nobody reviews. Foreign exchange executed at a spread the office has never asked about.
The rule we apply is short: ask every firm, in writing, what it receives from any third party in connection with the family's account, and ask for the figure in money for the last twelve months. A firm that needs a month to answer does not know. A firm that declines to answer has answered.
One page, once a year
It is a dull document, and it works. One page, every external relationship on it, once a year: what was invoiced, what was received from third parties, what the agreed scope was, what actually got done, and when the terms were last opened.
The first time a family does this, two things tend to happen. Somebody finds a mandate nobody in the room remembers signing. And the total comes out larger than the figure the principal or the team had in mind, usually by a margin that changes the conversation.
There is a second reason to hold the review. Across 146 offices studied by Campden Wealth in 2025, only about a quarter described the service they receive from their external providers as consistently excellent. Fees agreed when a relationship was working are still being paid on relationships that have since drifted, and the drift shows up faster when the money is on one page.
If the page has never been built, the calculator is a reasonable first draft of it. Three short sets of questions give the running cost of the office by expense line. The full analysis behind it, prepared on the same answers, gives the investment layer pocket by pocket, with three return scenarios and the total cost as a share of the gain. It will not replace the invoices. It will tell you, before you have gathered them, what order of magnitude to expect and where to look first.
How we help
We map what a family pays externally, test it against what comparable offices pay for equivalent work, and help adjust it where the terms no longer fit. That is the cost review within our family office audit: one all-in figure, benchmarked, with every fee layer on the same page.
A family that knows what it pays outward, to whom, and for what, can renegotiate any part of it. A family that has never assembled the page has nothing to renegotiate from.
Frequently asked questions
What are the most common fee structures for family offices?
There are five different ways a family pays for services, and most arrangements combine two or three of them. A percentage of assets under management, standard in portfolio mandates. A fixed fee for a defined scope over a defined period, standard in administration and accounting and now spreading into advisory work. Time billed by the hour, standard for legal and tax work. A fee on an event, such as a transaction or a success fee on a sale. And money the firm receives from a third party in connection with the family's account, which the family pays without ever seeing an invoice.
Does a family pay more to invest than to run its family office?
For a portfolio of ordinary complexity, yes. Our cost calculator prices a $500m office holding half its assets in listed markets, close to a third in private and real asset funds and a tenth in direct holdings at roughly $3.3m a year to run, or 66 basis points. Investing the money costs about $6.3m a year, or 126 basis points: some $4.6m paid to managers, funds, custodians and brokers, and about $1.7m of carried interest spread over the life of the funds. That makes 192 basis points in all. Even without the carry, investing costs more than running the office. On a purely listed portfolio of the same size the two halves come much closer together. Complexity is what tips the balance.
How do investment fees compare between family offices and other wealth advisers?
The two figures measure different things, so the comparison only works once both are assembled in full. Bank surveys put a single family office's own running cost at around 41 basis points of assets on average, covering salaries, premises and systems. That is a fair number for an average office, and not necessarily for yours. On top of that sit the fees the office pays to managers, banks and administrators, which are usually the larger half. An external wealth adviser quotes one rate covering both its operation and its judgement. Price your own running cost with our family office cost calculator, then compare the whole bill on each side in money. Comparing rates alone misleads.
What is a retrocession, and how does a family find out if it is paying one?
A retrocession is a payment a fund, platform or product provider makes to the firm that placed the family's money there. Trailer commissions, platform rebates and share-class differentials work the same way. The family pays it inside the product rather than through an invoice, so it does not appear in the budget. The way to find out is to ask every firm in writing what it receives from any third party in connection with the family's account, and to ask for the figure in money over the last twelve months.
How often should a family review what it pays external providers?
Once a year, on a single page, with every relationship listed in money rather than in percentages. Anything more frequent turns into a standing agenda item nobody prepares for. Anything less frequent and mandates drift for long enough that the terms are no longer the ones anybody agreed to.